If you are self-employed, ask yourself one important question:
What happens to your income if you cannot work for six months?
For a business owner or independent professional, a disability can create two problems at once. Your household income may stop, while many of the expenses required to keep your business running continue.
That is why disability insurance for self-employed professionals deserves serious consideration.
Across Upstate South Carolina, many contractors, consultants, practice owners and small-business owners insure their homes, vehicles, equipment and businesses. But the asset that produces the income to pay for all of those things is often overlooked:
"Your Ability to Work and Earn an Income"
How Much Disability Insurance Can a Self-Employed Person Buy?
Disability insurance companies generally look at the income you personally earn from the business, not simply your gross business revenue.
For example, if your business generates $250,000 a year but requires $150,000 in legitimate operating expenses, the full $250,000 would not normally be treated as your personal insurable income.
The exact amount a carrier recognizes can depend on how your business is structured and how your income is reported.
Underwriters may review:
Schedule C income
W-2 wages
K-1 statements
Business and personal tax returns
Other financial documentation
Some carriers may review one year of income, while others may ask for two or more.
There is no single formula used by every insurance company.
What Does the 60% Rule Mean?
A common rule of thumb is that disability insurance may replace roughly 60% of income.
That is only a starting point.
Insurance companies establish their own financial underwriting limits based on income, occupation, existing coverage and other factors. Long-term disability coverage commonly replaces a portion of pre-tax income rather than 100%.
For example, someone earning $100,000 per year might qualify for a monthly disability benefit around $5,000, but the actual amount depends on the carrier.
A better question is:
How much monthly income would your household actually need if your paycheck stopped tomorrow?
Start With the Bills That Do Not Stop
Before choosing a benefit amount, look at the expenses your household would still have during a disability:
Mortgage or rent
Utilities
Groceries
Health insurance
Vehicle payments
Credit obligations
Childcare
Other essential expenses
Then subtract income that might still be available from a spouse, savings or other sources.
The difference helps identify the monthly income gap you may want to protect.
Personal Disability Insurance vs. Business Overhead Expense Coverage
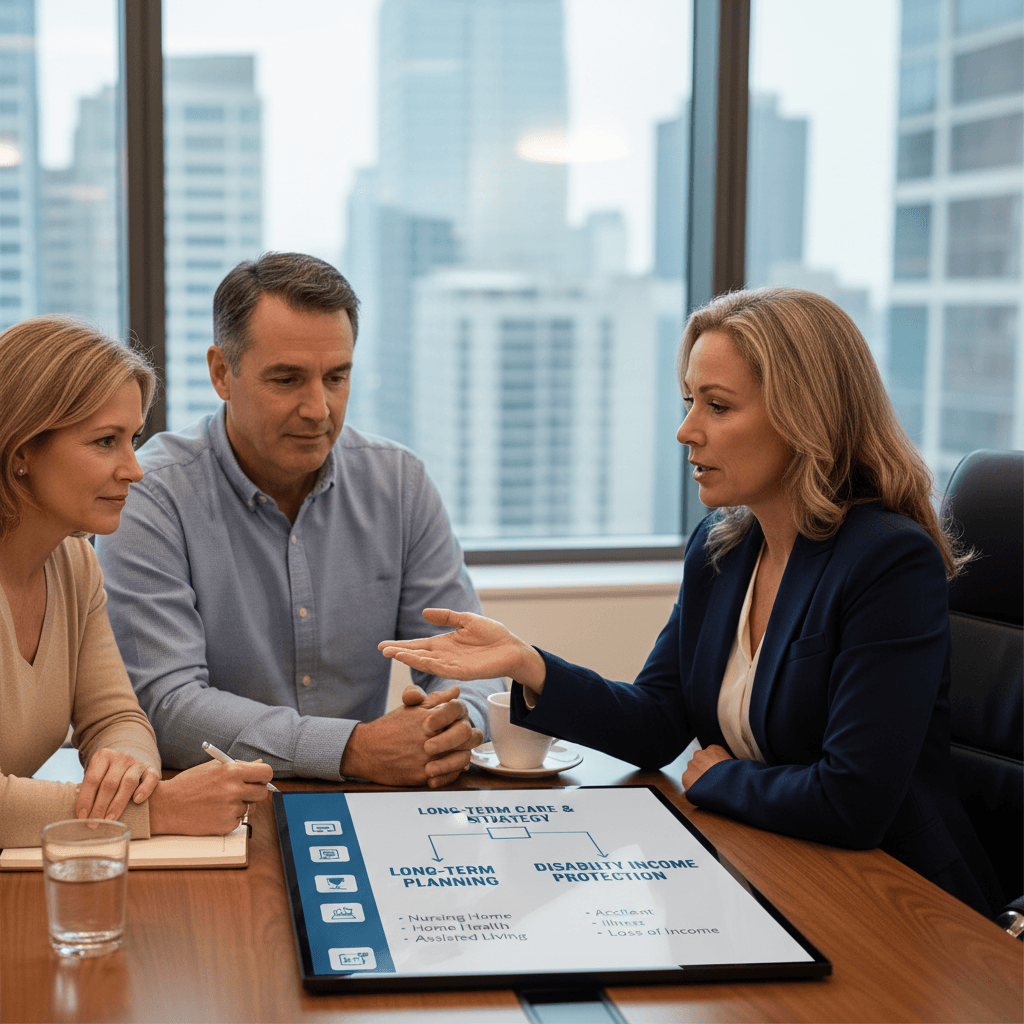
This is one of the most important distinctions for self-employed professionals. Individual disability income insurance is designed to replace part of your personal earned income if illness or injury prevents you from working.
But what about the business?
Even while you are disabled, the business may still owe:
Rent
Utilities
Employee salaries
Equipment leases
Insurance premiums
Accounting and professional fees
That is where Business Overhead Expense disability insurance, often called BOE coverage, may help.
BOE coverage is designed to reimburse qualifying business expenses during a covered disability. Recent self-employed disability guidance continues to distinguish personal income protection from BOE protection for the business itself.
Think of it this way:
Personal disability insurance helps protect your household.
Business Overhead Expense coverage helps protect the business.
For some owners, both may be appropriate.
Own Occupation vs. Any Occupation
The definition of disability inside the policy can be just as important as the benefit amount.
An own-occupation definition generally focuses on whether you can perform the material duties of your occupation.
An any-occupation definition is usually more restrictive and may require that you be unable to work in another occupation for which you are reasonably suited under the terms of the policy.
This can matter greatly for specialized professionals. A surgeon may no longer be able to operate but could still teach medicine. A contractor may no longer be able to perform physical labor but could work behind a desk. That is why disability insurance should not be compared on price alone.
Short-Term vs. Long-Term Disability Insurance
Short-term disability insurance is designed for shorter periods of disability, often lasting weeks or months.
Long-term disability insurance is designed for more serious illnesses or injuries that may prevent someone from working for years. Recent 2026 guidance for self-employed workers continues to emphasize long-term coverage as protection against the more serious income-loss risk.
One important choice is the elimination period, or how long you must remain disabled before benefits begin.
If you have enough emergency savings to cover several months of expenses, choosing a longer elimination period may help lower the cost of disability insurance while still protecting against a long-term financial loss.
What About Taxes?
For an individually owned disability policy, premiums paid personally with after-tax dollars are generally not deductible. Qualifying benefits are generally received income-tax free.
Business Overhead Expense coverage is handled differently. Premiums may generally be deductible as a business expense, while benefits used to reimburse business expenses are generally taxable.
Because tax situations vary, business owners should review their circumstances with a qualified tax professional.
The Question Every Self-Employed Professional Should Ask
Most business owners insure their buildings, vehicles, equipment and liability exposure. But, what asset produces the money that pays for all of those things?
For many self-employed professionals, the answer is simple: their ability to work.
Ask yourself: How long could you continue paying your household and business expenses if your income stopped today?
If the answer makes you uncomfortable, disability income insurance is definitely worth reviewing.
Helping Upstate South Carolina Business Owners Protect Their Income
At the Shanley Insurance Agency, we have been helping individuals, families and small business owners throughout Upstate South Carolina make insurance decisions since 1999.
As an independent agency, we can help compare disability insurance for self-employed professionals, long-term disability insurance, policy definitions, elimination periods and Business Overhead Expense options.
We start with three questions:
How much income does your household actually need each month?
How long could you continue paying your bills without working?
Which business expenses would continue during a disability?
If you are self-employed in Greenville, Pickens, Easley, Clemson, Anderson, Seneca or elsewhere in Upstate South Carolina, Contact the Shanley Insurance Agency today for your personal.
Sometimes the right answer is more coverage. Sometimes it is less. The important thing is knowing where you stand before an illness or injury forces the decision for you.
Local. Independent. Experienced. Trusted since 1999.