If a serious illness or injury stopped you from working tomorrow, how long could your business keep paying your bills? For most self-employed South Carolinians, the honest answer is a few months, maybe less. Long term disability insurance is the safety net that keeps your income coming when you cannot deliver the work that pays for everything else.
Need answers now? Call the Shanley Insurance Agency at (864) 868-5194 or send us a message and we will help you protect the income your business runs on.
As your own boss, your ability to earn is your most valuable asset, and there is no HR department standing behind it. Here is the plan for this guide: what long term disability actually covers, why the 'own occupation' wording matters more than you think, what it realistically costs, and how to get covered the right way. By the end, you will know exactly what to ask for.
Your Business Has One Point of Failure: You
Every business has a single point of failure. For the freelancer or owner-run shop in Pickens and Easley, that point is you. Most owners insure their building, their equipment, and their health, then overlook the one loss that could shut everything down: their ability to show up and earn. No income, no business, no backup.
Long term disability insurance for self employed South Carolina residents replaces a big share of that income when a health problem drags on for months or years. It is predictable, private, and built around your work, not a government formula. That is the difference between a hard season and a financial wipeout.
Here is the honest math most owners learn too late: one serious accident or diagnosis can mean a year without income, and a year of bills does not stop just because the work did.
Where Does Your Income Go When the Work Stops?
Short term disability handles the small stuff, a three to six month bridge for a surgery or a short illness you recover from. Long term disability is different, and it is the one that matters most. It keeps paying you a monthly check for years, or even until retirement age, when the setback is serious enough to end your career.
In between sits a waiting window called the elimination period, usually 90 or 180 days, the gap from your last day of work to your first check. That gap is exactly what your emergency fund is for.
Treat your savings as your own first line of defense. Keep three to six months of expenses set aside, then choose a long term policy with a 90 or 180 day waiting period to match it. That way you only buy the expensive income protection you actually need.
Own Occupation: The Four Words That Decide Everything
Here is where the fine print pays your claim or sends it back denied. The standard you want is called True Own or Owners Occupation: the policy pays if a health condition stops you from doing your own specific job, even if you could still work a different job. That protection matters most to people whose income comes from years of hard-won skill.
Cheaper policies use an Any Occupation rule instead, and so does Social Security Disability. Under that language, if the insurer decides you could do any job you are reasonably qualified for, they can deny you. For a specialist, the difference is a livable check versus a stack of bills.
Picture an orthopedic surgeon in Greenville who develops a slight hand tremor. His surgical career is over, but he could still teach or consult. With Own Occupation language, he is paid because he can no longer operate. With Any Occupation, the insurer might argue he should take a desk job instead.
The same rule holds for the contractor in Pickens County whose knee gives out on the job site. You should not be forced into a sedentary office job just because you can technically sit at a computer. The right definition protects the specific value you bring, which is exactly why disability insurance for self employed professionals rewards expert guidance.
What Does This Actually Cost?
Plan on roughly 1% to 3% of your annual income. For a professional in Easley earning $100,000, that is about $80 to $250 a month. The range is wide because no two policies are alike.
Age and health set a baseline, but your occupation class usually moves the number most. A graphic designer at a home office in Pickens pays far less than a roofing contractor running a crew across the Upstate, because carriers price the odds of a career-ending injury differently by trade.
That is why shopping one carrier is never enough. An independent agency compares several companies so your premium reflects your actual job, not a generic category. The goal is coverage that reads like a fixed business expense, not a burden.
Two Dials That Quietly Shape Your Price
Two simple choices control most of the price. The first is your waiting period: stretching it from 90 to 180 days noticeably lowers your premium, and it works well if you have cash set aside to cover those first months. The second is how long the benefit lasts, typically 2, 5, or 10 years, or all the way to age 67.
"How our agency helps business owners is by presenting a short-term disability plan that is designed to cover the first 3 to 6 months of a disability. Then have a secondary long-term disability plan in place with a 180 day waiting period to take over if the disability lasts longer than 6 months. This can help keep your costs down".
Coverage to age 67 is the most secure, the choice that keeps a permanent disability from quietly draining your retirement. A 5 or 10 year benefit can still be a smart, leaner bridge while your business is growing.
The right pairing depends on your savings and where your business is headed, which is why a quick review of the numbers beats guessing at a screen.
Let Us Help You Get This Right
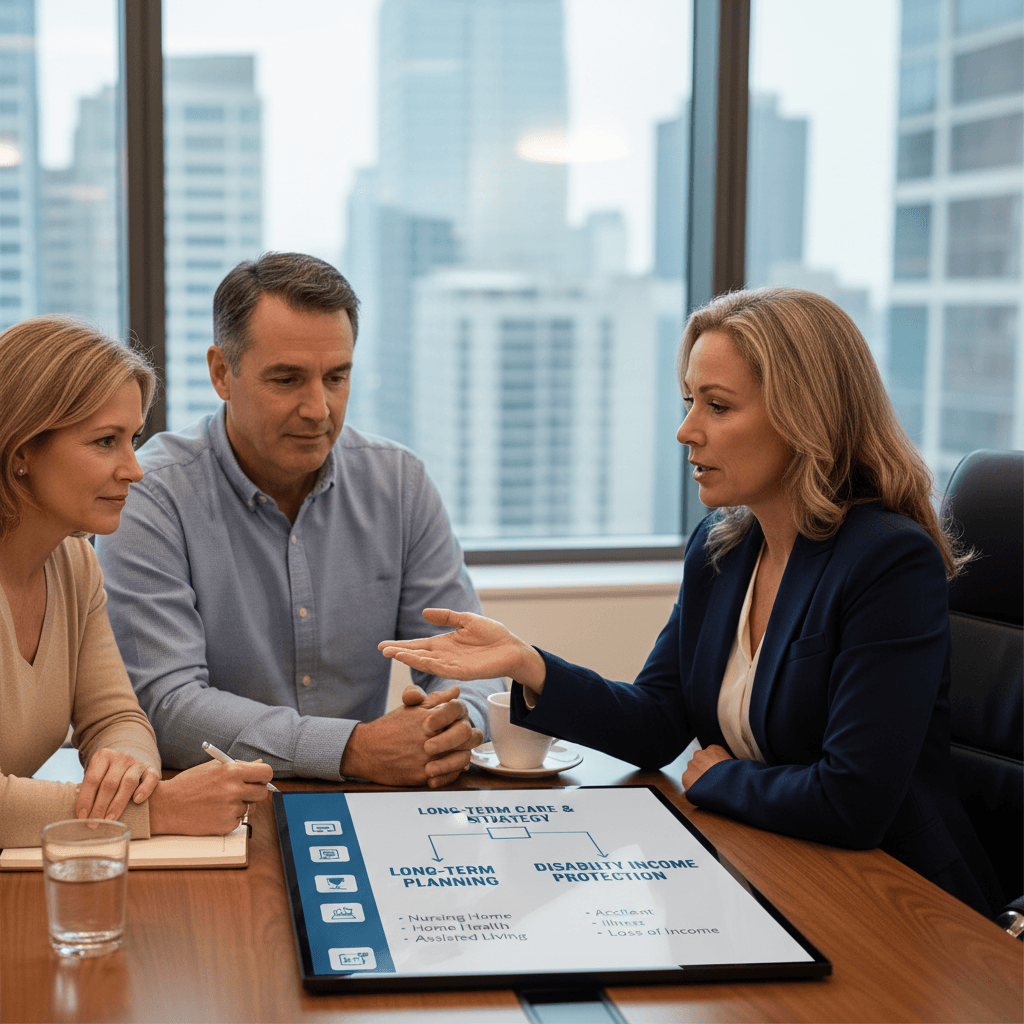
You run a business, so you do not have spare hours to click through generic online calculators that miss the details of life in the Upstate. Getting long term disability right means making sure the actual contract contains the own occupation language your trade depends on, and an independent agent works for you, not a single carrier.
At the Shanley Insurance Agency, we bring the office to you with phone or in-home appointments across the Upstate, so your coverage never costs you a trip during working hours. Since 1999, we have helped self-employed families and business owners protect what they have built, through Living Benefits and disability income protection built around your real world.
Your ability to earn pays for everything else, so it deserves the strongest plan you can put behind it. Own occupation wording, the right wait period, the right benefit length, these details decide whether you are protected or just paying for a piece of paper. You do not have to sort it out alone. Contact our office today and, let us walk you through it, so the next surprise in your health never becomes a surprise in your budget.
Get your free coverage review. Call Shanley Insurance Agency at (864) 868-5194 or send us a message and we will help you lock in the right plan for your work.